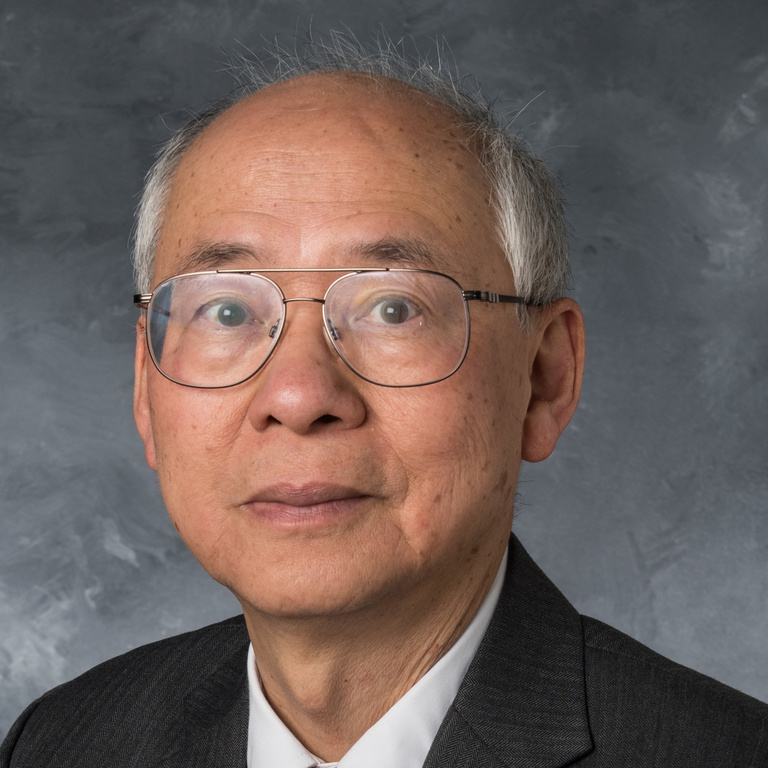
Elias S.W. Shiu
From 1976 to 1991, Elias S.W. Shiu was a professor of actuarial mathematics at the University of Manitoba and a consultant to the Great-West Life Assurance Company, Winnipeg, Canada. He joined the University of Iowa in 1992 as Principal Financial Group Professor. He is an Honorary Editor of the journal Insurance: Mathematics and Economics and was a Co-Editor of the North American Actuarial Journal. His paper “Option Pricing by Esscher Transforms” is the most-cited paper ever published in the Transactions of the Society of Actuaries. Another paper, “On the Time Value of Ruin,” served as the theme of a biennial international conference series from 2006 to 2018. Both papers were co-authored with Hans U. Gerber. His research papers have won four Halmstad Prizes. The Society of Actuaries presented him an Annual Prize (with H.U. Gerber in 1995), an Edward A. Lew Award (with H.U. Gerber in 1999), and a Presidential Award (in 2026). He was awarded Doctor of Actuarial Science, honoris causa, by Université de Lausanne in 2017 and Doctor of Science, honoris causa, by The Hang Seng University of Hong Kong in 2024.
Selected courses taught
- ACTS:4130 Quantitative Methods for Actuaries, Fall 2024
- ACTS:4180 Life Contingencies I, Spring 2025
- ACTS:4280 Life Contingencies II, Fall 2025
- ACTS:6160 Topics in Actuarial Science: Actuarial Applications of Finance, Spring 2026
- STAT:5120 Mathematical Methods for Statistics, Spring 2023
Selected publications
- Gerber, H. U., Shiu, E. S. W. (2025). Uniform Distribution of Deaths, Fractional Independence, and Negative Payment-Frequency. North American Actuarial Journal, 29, 478–493.
- Gerber, H. U., Shiu, E. S. W. & Yang, J. (2021). An Actuarial Approach to Pricing Barrier Options. European Actuarial Journal, 11, 333–339.
- Gerber, H. U., Shiu, E. S. W. & Yang, H. (2019). A Constraint-free Approach to Optimal Reinsurance. Scandinavian Actuarial Journal, 2019(1), 62–79.
- Gerber, H. U., Shiu, E. S. W. & Yang, H. (2015). Geometric Stopping of a Random Walk and Its Applications to Valuing Equity-linked Death Benefits. Insurance: Mathematics and Economics, 64, 313–325.
- Gerber, H. U., Shiu, E. S. W. & Yang, H. (2013). Valuing Equity-Linked Death Benefits in Jump Diffusion Models. Insurance: Mathematics and Economics, 53, 615–623.
- Ko, B., Shiu, E. S. W. & Wei, L. (2010). Pricing Maturity Guarantee with Dynamic Withdrawal Benefit. Insurance: Mathematics and Economics, 47, 216–223.
- Gerber, H. U., Shiu, E. S. W. (2005). The Time Value of Ruin in a Sparre Andersen Model. North American Actuarial Journal, 9(2), 49–69; Discussions 69–84 & 9(4), 131–136.
- Gerber, H. U., Shiu, E. S. W. (2004). Optimal Dividends: Analysis with Brownian Motion. North American Actuarial Journal, 8(1), 1–20.
- Gerber, H. U., Shiu, E. S. W. (2003). Pricing Perpetual Fund Protection with Withdrawal Option. North American Actuarial Journal, 7(2), 60–77; Discussions 77–92 & 8(1), 96–99.
- Gerber, H. U., Shiu, E. S. W. (2000). Investing for Retirement: Optimal Capital Growth and Dynamic Asset Allocation. North American Actuarial Journal, 4(2), 42–58; Discussions 58–62.
- Gerber, H. U., Shiu, E. S. W. (1996). Actuarial Bridges to Dynamic Hedging and Option Pricing. Insurance: Mathematics and Economics, 18, 183–218.
- Gerber, H. U., Shiu, E. S. W. (1996). Martingale Approach to Pricing Perpetual American Options on Two Stocks. Mathematical Finance, 6, 303–322.
- Shiu, E. S. W. (1990). On Redington's Theory of Immunization. Insurance: Mathematics and Economics, 9, 171–176.
- Actuarial science
- Financial mathematics
- Quantitative risk management